

A PayPal chargeback occurs when a buyer skips PayPal’s Resolution Center entirely and disputes a charge directly with their credit card issuer or bank. This means the card network, not PayPal, decides whether you keep the sale. PayPal charges a $20 fee regardless of who wins.
For sellers, chargebacks hit harder than standard PayPal disputes because banks tend to favor cardholders and the evidence bar is higher. This guide covers how the process works, what separates chargebacks from PayPal’s internal dispute system, and the specific steps that give you the best chance of winning when one lands in your account.
What Are PayPal Chargebacks
A PayPal chargeback happens when a buyer bypasses PayPal entirely and files a dispute directly with their credit card issuer or bank. The card issuer, not PayPal, makes the final decision, and PayPal charges a $20 fee regardless of who wins. According to Mastercard’s 2025 State of Chargebacks report, the global cost of chargebacks to merchants is forecast to climb toward $42 billion by 2028, with nearly half tied to fraud claims, underscoring why understanding this process matters more than ever.
How PayPal Chargebacks Work for Sellers
Here’s how the PayPal chargeback process typically unfolds. First, a cardholder contacts their bank claiming an unauthorized transaction, an item they never received, or a product that arrived significantly different from what was described. The bank then pulls the disputed funds from PayPal, and PayPal places a temporary hold on your account for that amount.
What makes chargebacks particularly frustrating is the fee structure. Even if you win the case and keep the sale, you’re still out $20. That alone makes prevention far more cost-effective than fighting chargebacks after they land in your inbox.
The most common triggers include:
- Unauthorized transaction claims: The cardholder says they didn’t make or approve the purchase.
- Item not received: The buyer claims the order never arrived.
- Significantly not as described: The product differs materially from the listing.
- Duplicate charges: The customer was billed more than once.
One detail that catches many sellers off guard: buyers can file chargebacks up to 180 days after the transaction date. That means you might face a dispute on an order you shipped six months ago. Keeping detailed records for at least that long is essential if you want any chance of mounting a defense.
PayPal Chargeback vs. Dispute vs. Claim
These three terms describe different processes, and confusing them can cost you money. For a fuller breakdown of how these mechanisms differ, this chargeback primer for merchants is a useful reference. A PayPal dispute starts in PayPal’s Resolution Center, where buyer and seller communicate directly to work things out. If they can’t reach an agreement, the buyer can escalate to a claim, and PayPal steps in to review evidence and decide.
A chargeback, on the other hand, bypasses PayPal completely. The buyer goes straight to their card issuer, and the bank’s rules determine the outcome.
| Type | Who Decides | Where It's Filed | Typical Timeline |
|---|---|---|---|
| Dispute | Buyer and seller negotiate | PayPal Resolution Center | 20 days to escalate |
| Claim | PayPal | PayPal Resolution Center | Usually 14 days, up to 30+ |
| Chargeback | Card issuer | Buyer's bank | Up to 30 days for PayPal to dispute it, plus up to 75 days for the card issuer to decide — roughly 30 to 105 days end-to-end |
Chargebacks are generally harder to win than internal PayPal disputes. Banks tend to favor cardholders, and the evidence requirements are stricter. You also lose control over the timeline since card networks set the deadlines, not PayPal.
Here’s something else to watch for: a single transaction can trigger both a PayPal dispute and a chargeback if the buyer pursues both channels at once. When that happens, the chargeback typically takes precedence, and PayPal closes the internal dispute automatically.
How to Fight a PayPal Chargeback
When PayPal notifies you of a chargeback, you typically have only 10 days to respond through the Resolution Center. Missing that window means an automatic loss, so treat every notification as urgent.
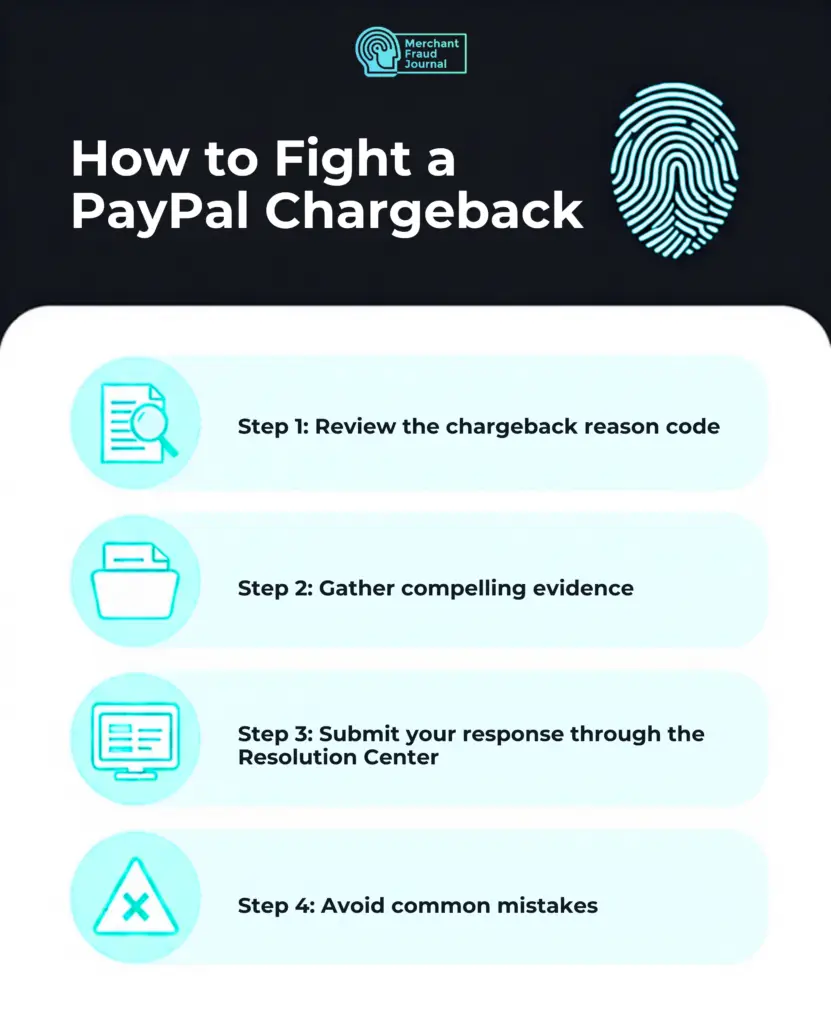
Step 1: Review the chargeback reason code
The chargeback reason codes tell you exactly what the buyer claimed. An unauthorized transaction dispute calls for different evidence than an item not received claim. Tailor your response to address the specific allegation rather than submitting generic documentation.
Step 2: Gather compelling evidence
Strong evidence directly contradicts the buyer’s claim. For unauthorized transaction disputes, you want proof that the legitimate cardholder made the purchase—matching IP addresses, previous order history, or device fingerprints all help. For item not received claims, tracking information showing delivery to the exact address on the PayPal transaction is critical.
Evidence that strengthens your case:
- Tracking with delivery confirmation: Shows the package reached the buyer’s address
- Signature confirmation: Required for orders over $750 and strongly recommended for high-value items below that threshold
- Communication logs: Emails or messages where the buyer acknowledged receipt or discussed the product
- Screenshots of product listings: Proves what was advertised matches what was shipped
- IP address and device data: Links the transaction to the buyer’s known devices
Step 3: Submit your response through the Resolution Center
Upload all documentation through PayPal’s Resolution Center before the deadline. This part of the process, known as chargeback representment, rewards organization — banks review hundreds of cases, and a well-structured response stands out. Include a brief written summary explaining how your evidence refutes the buyer’s claim.
Step 4: Avoid common mistakes
Sellers often lose winnable cases by submitting incomplete evidence or missing deadlines. Other frequent errors include providing tracking that shows delivery to a different address than what’s listed in PayPal’s transaction details, or failing to include signature confirmation on high-value orders. Tracking your own chargeback win rate over time can reveal whether these mistakes are a recurring pattern in your process.
Tip: Screenshot your PayPal transaction details page immediately when you receive a chargeback notification. This preserves the shipping address on record in case the buyer later claims a different address.
PayPal's Seller Protection Program
PayPal’s Seller Protection program can cover you for certain chargebacks, but eligibility requirements are strict. When protection applies, PayPal covers the full transaction amount and waives the chargeback fee.
Seller Protection typically covers two scenarios: unauthorized transaction claims and item not received disputes. However, you only qualify if you meet all of PayPal’s requirements at the time of the original transaction.
Eligibility requirements include:
- Ship to the address on the Transaction Details page: Shipping to any other address disqualifies you
- Provide valid tracking: Online tracking showing delivery to the correct address
- Signature confirmation for orders over $750: Without it, high-value orders aren’t protected
- Respond to PayPal’s requests within the deadline: Late responses void protection
What Seller Protection doesn’t cover:
- Significantly not as described claims: If the buyer says the item differs from the listing, you’re on your own
- Digital goods and services: Most intangible products are excluded
- In-person transactions: Seller Protection applies primarily to shipped goods
- Items picked up locally: No shipping means no tracking, which means no protection
Before assuming you’re covered, check the specific transaction in your PayPal account. Not all payment types qualify, and some business categories face additional restrictions.
Preventing Chargebacks Before They Happen
The most effective chargeback strategy is preventing disputes from occurring in the first place. Following chargeback prevention best practices from the start can dramatically reduce your exposure.
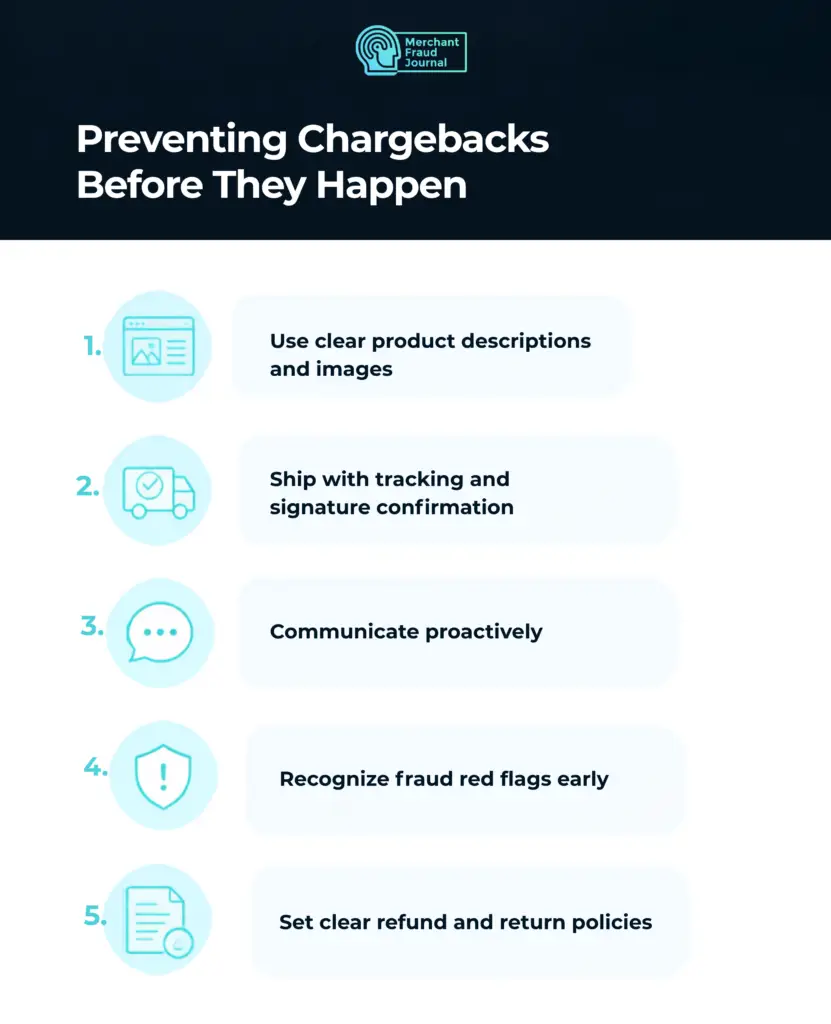
1. Use clear product descriptions and images
Vague listings lead to not as described disputes. Include accurate measurements, materials, colors, and multiple photos from different angles. If there are known limitations or imperfections, disclose them upfront—buyers who know what to expect rarely file chargebacks.
2. Ship with tracking and signature confirmation
Always use trackable shipping methods and require signature confirmation for orders over $750 (or lower, depending on your risk tolerance). The tracking number creates a paper trail that buyers can’t easily dispute.
3. Communicate proactively
Send shipping confirmations with tracking numbers immediately after dispatch. If there are delays, notify the buyer before they start wondering where their order is. Many chargebacks stem from impatience or confusion that a simple email could have prevented.
4. Recognize fraud red flags early
Certain patterns suggest a transaction may result in a chargeback, and many overlap with the signals used to spot friendly fraud:
- Mismatched billing and shipping addresses: Especially to freight forwarders or P.O. boxes
- Rush shipping requests on high-value orders: Fraudsters want goods before the card is reported stolen
- Multiple failed payment attempts: Could indicate testing stolen card numbers
- First-time buyers with unusually large orders: Legitimate customers typically start small
When red flags appear, consider canceling the order and refunding proactively. A voluntary refund costs nothing; a chargeback costs at least $20 plus the transaction amount.
5. Set clear refund and return policies
Publish your policies prominently and make the return process easy. Buyers who can get a refund directly from you have no reason to involve their bank. A generous return policy often reduces chargebacks more than it increases returns.
What Happens If You Lose a Chargeback
Losing a chargeback means the disputed funds are permanently removed from your account, and you forfeit the merchandise. The $20 chargeback fee is non-refundable regardless of outcome. According to LexisNexis Risk Solutions’ True Cost of Fraud study, US merchants now absorb an average of $4.61 in total costs for every $1 lost to fraud once fees, labor, and lost goods are factored in.
Beyond the immediate financial hit, chargebacks affect your account standing. PayPal monitors your chargeback ratio, and excessive disputes can trigger account reviews, reserves (where PayPal holds a percentage of your funds), or even account termination.
If you believe the decision was wrong, you may have limited appeal options depending on the card network involved. However, appeals are rarely successful without new evidence that wasn’t available during the initial dispute.
For merchants with high chargeback rates, the consequences compound. Both Visa’s dispute monitoring program and Mastercard’s excessive chargeback program impose fines on merchants exceeding threshold ratios. While these programs technically apply to your payment processor, the costs inevitably flow down to you through higher fees or terminated accounts.
The best response to a lost chargeback is analyzing what went wrong and adjusting your processes. Was the evidence insufficient? Did you miss a deadline? Could better communication have resolved the issue before it escalated?
Turning Chargeback Risk Into a Manageable Process
PayPal chargebacks bypass PayPal’s internal systems entirely, putting the decision in the hands of card issuers who typically favor buyers. Fighting them successfully requires fast action, organized evidence, and an understanding of what Seller Protection does and doesn’t cover.
Prevention remains your strongest defense. Clear listings, trackable shipping, proactive communication, and reasonable return policies eliminate most disputes before they start. When chargebacks do occur, respond within the deadline with evidence that directly addresses the buyer’s specific claim.
The $20 fee per chargeback is just the beginning. Account standing, processing relationships, and operational time all suffer when disputes pile up. Treating chargeback prevention as a core business function, rather than an occasional nuisance, protects both your revenue and your ability to accept payments long-term.
Frequently Asked Questions
Can a buyer file a chargeback after receiving a refund?
Yes, buyers can file chargebacks even after you've issued a refund, though this typically constitutes friendly fraud. If this happens, submit the refund confirmation as evidence to demonstrate the funds were already returned.
Does PayPal charge a fee just for receiving a chargeback, win or lose?
PayPal charges a $20 chargeback fee regardless of the dispute outcome. This fee is non-refundable even if you successfully defend the case and retain the transaction funds.
Can a PayPal chargeback affect my personal bank account if I'm not a business seller?
If your PayPal balance is insufficient to cover the chargeback amount and fees, PayPal may attempt to recover funds from your linked bank account or card. This applies to both personal and business accounts.
How many chargebacks before PayPal suspends or limits an account?
PayPal doesn't publish a specific threshold, but accounts with chargeback rates significantly above industry averages face reviews, reserves, or limitations. Keeping your ratio below 1% of transactions is a reasonable target.
Can a chargeback be reversed after it's already been decided?
Reversals after a final decision are rare and typically require new evidence that wasn't available during the original dispute. Some card networks allow limited appeals, but success rates are low.
Do PayPal chargebacks show up on a buyer's credit report?
Chargebacks don't appear on credit reports for buyers or sellers. However, if a chargeback results in a negative PayPal balance that goes to collections, that collection account could affect the account holder's credit.
Charity Amancio
Charity Amancio specializes in SaaS solutions for global eCommerce businesses, including payments and risk management applications. She bridges the gap between technology and merchant needs, offering practical perspectives on the tools shaping eCommerce. Her insights appear regularly in B2B publications covering the digital commerce space.