• Latest
VISA Amends Its Dispute Management Guidelines for Merchants

Visa VAMP Explained and How Merchants Stay Under the 2026 Thresholds

June 23, 2024 - Updated On November 17, 2026
Mastercard First-Party Trust program expands into Europe, represented by the Mastercard logo beside the European Union flag, symbolizing stronger payment security and collaboration to combat friendly fraud.

Mastercard Brings First-Party Trust Friendly Fraud Program to Europe

November 17, 2026
Silver handcuffs beside Bitcoin coins and a U.S. Department of Justice folder, with a prominent “$400 Million in Crypto Theft” headline, representing the DOJ's disruption of a North Korean deepfake cryptocurrency theft scheme.

DOJ Disrupts North Korean FaceStealer Deepfake Scheme Tied to $400 Million in Crypto Theft

November 17, 2026
A shopper authorizes a secure payment using a fingerprint scanner beside a bank card and shopping packages, while a glowing digital shopping cart and checkmark represent OpenAI's ChatGPT Wallet enabling AI agents to complete purchases on users' behalf.

OpenAI Launches ChatGPT Wallet to Let AI Agents Check Out for Shoppers

November 16, 2026
A black Rain single-use payment card displayed beside a secure digital Agent Vaults interface, illustrating how AI agents can make controlled payments using single-use cards with spending limits and security protections.

Rain Launches Agent Vaults With Single-Use Cards for AI Agent Payments

November 16, 2026
A judge’s gavel hovers above its sound block beside Visa and Mastercard payment cards and merchant receipts in a courtroom setting. The graphic highlights the November 16 final approval hearing for the swipe-fee settlement affecting approximately 12 million U.S. merchants.

Visa and Mastercard Swipe Fee Settlement Heads to Final Approval Hearing Nov. 16

November 13, 2026
A robotic arm places an oversized red coat into a shopping basket, while a balance scale holds two payment cards on opposite sides of a receipt, symbolizing AI shopping mistakes and the dispute over who bears financial responsibility.

Who Pays When an AI Shopping Agent Buys the Wrong Thing? Payment Firms Split on Liability

November 12, 2026
A Fingerprint-branded fraud detection display showing a color-coded Fraud Score gauge, representing the launch of personalized fraud scoring models trained on each customer's own data.

Fingerprint Launches Fraud Score to Train Fraud Models on Each Customer’s Own Data

November 12, 2026
A customer taps a blue payment card on a point-of-sale terminal, which displays a green approval checkmark. Subtle digital data connections link the payment terminal to a bank symbol in the background, representing Global Payments’ integration of Visa Intelligent Data Exchange (IDX) API into its Adaptive Authentication platform to reduce false declines and improve legitimate transaction approvals.

Global Payments Adds Visa IDX API to Adaptive Authentication to Fight False Declines

November 12, 2026
A burlap money bag marked with a dollar sign sits beside a security shield and padlock, next to a navy sign highlighting Allstate's finding that nearly 60% of scam cases this year involve impersonation.

Allstate Data Shows Impersonation Behind Nearly 60% of Scam Cases This Year

November 11, 2026
A gavel rests on its sound block beside stacked wooden blocks reading “Shell Companies,” “Unauthorized Debits,” and “$3.7 Million,” with a document titled “Federal Charges” and credit cards in the foreground, set against a blurred background of law books.

Two Charged Over Shell Companies That Used Payment Processors to Attempt $3.7M in Unauthorized Debits

November 11, 2026
A person holds a magnifying glass over a glowing digital shopping cart icon, surrounded by connected icons representing a padlock shield, credit card, user profile, bar chart, location pin, and email, with the text “OSINT, Open-Source Intelligence” beside it — illustrating the use of open-source intelligence to investigate online shopping and e-commerce fraud.

What Is OSINT in Cybersecurity? A Guide for eCommerce Merchants

November 11, 2026
A whiteboard titled “Visa Benchmark: AI Shopping Agents” shows bar charts of error rates with the headline “AI Shopping Agents Failure Rate: FAIL 42.8% of Test Runs,” along with icons depicting failed test runs, failed shopping cart checkouts, and broken connections labeled “Broken connect failures in the action”; a desk below holds printed evaluation documents with highlighted text, colorful sticky notes, markers, and an open notebook with handwritten charts.

Visa Benchmark Finds AI Shopping Agents Fail 42.8% of Test Runs

November 10, 2026
  • Contribute
  • Contact Us
  • About
  • Join Us
  • Advertise
Tuesday, November 17, 2026
Merchant Fraud Journal
ADVERTISEMENT
  • Home
  • Articles
    • Chargebacks
    • Fraud Prevention
    • Influencer Insights
  • Resources
    • Recorded Webinars
    • Podcasts
    • Vendor Directory
    • eCommerce Fraud Reports
    • Training and Certifications
    • Jobs Board
    • Associations and Non-Profits
  • News
No Result
View All Result
  • Home
  • Articles
    • Chargebacks
    • Fraud Prevention
    • Influencer Insights
  • Resources
    • Recorded Webinars
    • Podcasts
    • Vendor Directory
    • eCommerce Fraud Reports
    • Training and Certifications
    • Jobs Board
    • Associations and Non-Profits
  • News
No Result
View All Result
Merchant Fraud Journal
No Result
View All Result

Visa VAMP Explained and How Merchants Stay Under the 2026 Thresholds

By: Charity Amancio | First published on: June 23, 2024 | Updated on: November 17, 2026

Visa VAMP, the Visa Acquirer Monitoring Program, is Visa’s single program for tracking fraud and disputes on card-not-present transactions. It replaced the Visa Dispute Monitoring Program and the Visa Fraud Monitoring Program on April 1, 2025, and it measures every merchant with one count-based ratio. That ratio adds fraud reports (TC40s) to disputes (TC15s) and divides the total by settled card-not-present sales. 

Since April 1, 2026, a merchant in the US, Canada, Europe, or Asia Pacific is identified as Excessive at a ratio of 1.5% or higher with at least 1,500 counted fraud reports and disputes in a month. Merchants who cross that line face per-item fees passed on by their acquirer, tighter account terms, and in the worst cases the loss of their merchant account.

What Is the Visa Acquirer Monitoring Program?

The Visa Acquirer Monitoring Program holds acquirers responsible for the fraud and dispute levels across the merchants they board. Visa watches each acquirer’s whole portfolio and each merchant inside it, and acquirers are expected to act when a merchant drifts above the limits. Visa first described the redesigned program in an August 2024 Visa announcement before it took effect in 2025.

Why Visa Replaced VDMP and VFMP

The older programs tracked disputes and fraud separately, so a merchant could sit just under both limits and still generate heavy losses. The Visa VAMP program combines both signals into a single number. It also shifts more responsibility onto acquirers, who now carry their own thresholds and pass consequences down to the merchants that push their portfolio ratio up.

How the VAMP Ratio Is Calculated

The VAMP ratio counts transactions instead of dollars, so a $5 dispute weighs the same as a $5,000 one. Visa’s VAMP fact sheet defines it as the count of fraud reports (TC40) plus disputes (TC15), divided by the count of settled card-not-present transactions (TC05) in the same month. Card-present sales are outside the calculation entirely.

Two examples show how the count minimum works. A store with 30,000 settled card-not-present sales, 300 fraud reports, and 200 disputes has a VAMP ratio of about 1.67%. It is above the percentage line but below the 1,500 count minimum, so it is not identified as Excessive. A larger store with 120,000 sales, 1,100 fraud reports, and 700 disputes has 1,800 counted items and a ratio of exactly 1.5%, which meets both conditions.

What Counts Toward the VAMP Ratio

Most merchants are surprised by how much the ratio includes. A single fraudulent transaction can count twice, once as a fraud report and once as a dispute. Knowing your Visa and Mastercard chargeback codes helps you see which category each case falls into.

  • TC40 fraud reports that issuers file when a cardholder says a transaction was unauthorized, even if no chargeback follows
  • TC15 disputes across fraud and non-fraud reason codes, including processing errors and consumer disputes
  • Fraud-related disputes resolved through Rapid Dispute Resolution (RDR) or Cardholder Dispute Resolution Network (CDRN) alerts, which still count after a March 2025 rule change
  • Card-not-present transactions only, both domestic and cross-border

Some cases stay out of the count. Non-fraud disputes resolved through RDR or CDRN and disputes resolved with Compelling Evidence 3.0 are excluded, which makes those tools valuable for keeping the dispute side of the ratio down.

Visa VAMP Thresholds for 2026

Visa applies separate thresholds to merchants and to acquirer portfolios, plus a separate test for card testing. The table below summarizes the limits in effect from April 1, 2026.

Program level VAMP ratio Minimum monthly count Where it applies
Merchant, Excessive 1.5% or higher 1,500 fraud reports and disputes US, Canada, Europe, Asia Pacific
Merchant, Excessive (CEMEA) 2.2% or higher Confirm count conditions with your acquirer Central Europe, Middle East, and Africa
Acquirer, Above Standard 0.5% to below 0.7% 1,500 fraud reports and disputes Acquirer portfolio
Acquirer, Excessive 0.7% or higher 1,500 fraud reports and disputes Acquirer portfolio
Enumeration (card testing) 20% or higher of authorization attempts 300,000 enumerated transactions Merchant level

The merchant Excessive line dropped from 2.2% to 1.5% on April 1, 2026, which pulled many growing stores into scope for the first time. Acquirers whose portfolios sit above standard also tend to set tighter internal limits for their merchants, so your practical ceiling may be lower than Visa’s published number.

The Enumeration Ratio and Card Testing

The enumeration ratio targets card testing, where bots run thousands of small authorizations to find working card numbers. It compares enumerated authorization attempts, both approved and declined, with all authorization attempts. A merchant meets the threshold at 20% or higher with at least 300,000 enumerated transactions in a month, which is why bot protection at checkout now matters for compliance as well as for losses.

VAMP Fees and Enforcement

Visa ran an advisory period after launch, and enforcement of the Excessive level began after it ended on September 30, 2025. In the US, a merchant identified as Excessive can be charged $8 for each counted fraud report and dispute. Visa bills the acquirer, and most acquirers pass the fee straight to the merchant under the terms of the processing agreement.

Fees are only part of the cost. Acquirers can add rolling reserves, raise rates, or require a remediation plan, and repeated identification can end the relationship. Merchants already on a high-risk merchant account usually have the least room, since their contracts often include stricter ratio covenants than the network limits.

How Visa VAMP Compares With Mastercard's Programs

Mastercard still runs separate programs for chargebacks and fraud. The Mastercard Excessive Chargeback Program starts at 100 chargebacks and a 1.5% ratio in a month, so the percentage matches Visa’s merchant line while the count minimum is far lower. 

Since July 24, 2026, Mastercard also requires acquirers to open an investigation within 72 hours when a merchant shows scam warning signs, including a combined refund and chargeback rate above 5% over a rolling 30-day window for newer merchants.

Persistent problems with either network can end in a listing on Mastercard’s MATCH terminated merchant file, which can block a business from opening new merchant accounts for five years. Tracking both networks together gives a more accurate picture of your risk than watching Visa alone.

How to Stay Under the Visa VAMP Thresholds

Staying compliant means lowering both halves of the ratio. Fraud reports fall when fewer stolen cards get through checkout, and disputes fall when customers get answers before they call their bank.
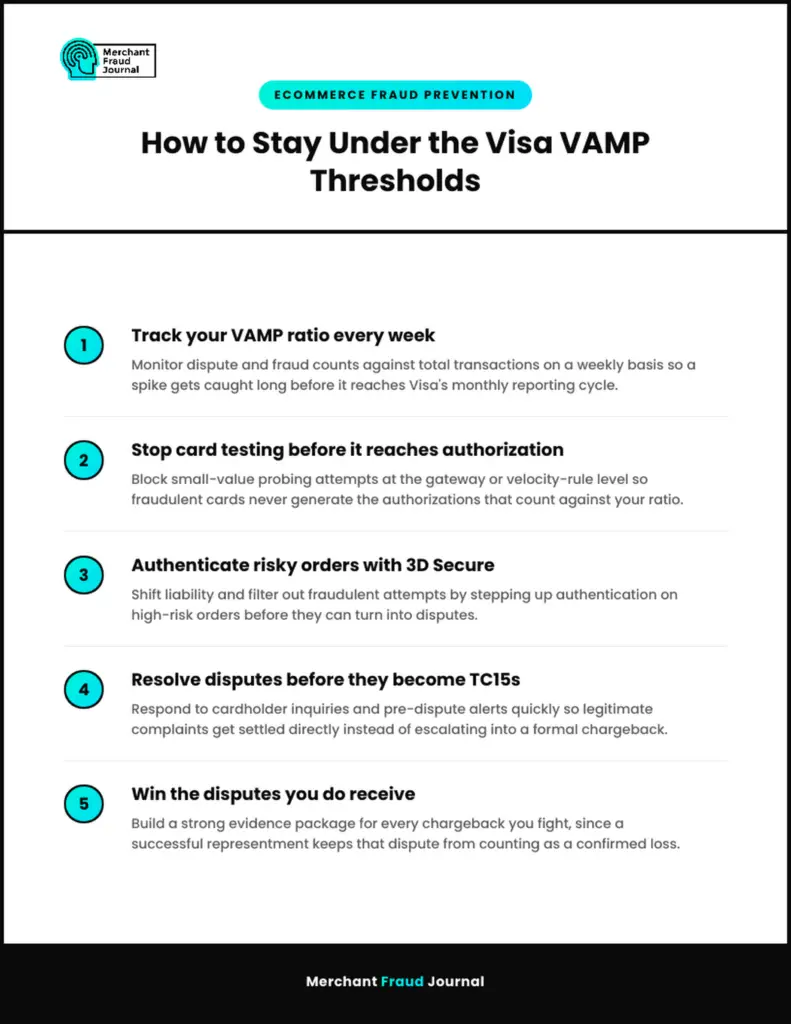
Merchant Fraud Journal infographic titled “How to Stay Under the Visa VAMP Thresholds,” tagged “Ecommerce Fraud Prevention,” with five numbered tips: 1) Track your VAMP ratio every week — monitor dispute and fraud counts against total transactions on a weekly basis so a spike gets caught long before it reaches Visa’s monthly reporting cycle; 2) Stop card testing before it reaches authorization — block small-value probing attempts at the gateway or velocity-rule level so fraudulent cards never generate the authorizations that count against your ratio; 3) Authenticate risky orders with 3D Secure — shift liability and filter out fraudulent attempts by stepping up authentication on high-risk orders before they can turn into disputes; 4) Resolve disputes before they become TC15s — respond to cardholder inquiries and pre-dispute alerts quickly so legitimate complaints get settled directly instead of escalating into a formal chargeback; 5) Win the disputes you do receive — build a strong evidence package for every chargeback you fight, since a successful representment keeps that dispute from counting as a confirmed loss.

1. Track Your VAMP Ratio Every Week

Most merchants learn their ratio from the acquirer, often weeks late. Build your own weekly count of fraud reports and disputes against settled card-not-present sales, and include it in your merchant fraud monitoring. A weekly view shows a spike while there is still time to act within the month.

2. Stop Card Testing Before It Reaches Authorization

Bot detection, velocity limits on cards per device, and CAPTCHA on repeated failed payments keep enumeration attacks from inflating both the enumeration ratio and later fraud reports. Rules that block a burst of low-value attempts from one device or IP range are usually the fastest win.

3. Authenticate Risky Orders With 3D Secure

Stepping up risky card-not-present orders to 3D Secure authentication stops many stolen-card purchases at checkout and generally shifts fraud liability for authenticated transactions to the issuer. Apply it selectively, since adding friction to every order can cost more in lost sales than it saves.

4. Resolve Disputes Before They Become TC15s

Pre-dispute tools such as RDR, CDRN alerts, and Order Insight let merchants refund or share order details before a dispute is filed. Non-fraud cases resolved this way stay out of the ratio, which matters most for subscription and digital goods merchants who see heavy friendly fraud. Clear billing descriptors and fast customer service reduce the number of cases that reach this stage at all.

5. Win the Disputes You Do Receive

Strong chargeback representment recovers revenue, and Compelling Evidence 3.0 can block eligible fraud disputes entirely when a cardholder has a history of undisputed purchases with your store. A well-documented chargeback rebuttal letter and a clear view of the chargeback process help, and merchants with high volumes often bring in one of the chargeback protection companies.

Treat the 1.5% Line as a Ceiling

Visa VAMP rewards merchants who manage fraud and disputes together. Measure the ratio weekly, block card testing at checkout, authenticate the orders that look risky, and resolve non-fraud complaints before they become disputes. Merchants who keep their ratio well below 1.5% avoid the fees, keep better terms with their acquirer, and have room to absorb a bad month without a compliance problem.

Frequently Asked Questions

These answers cover the questions merchants ask most often about the Visa Acquirer Monitoring Program.

What is Visa VAMP?

Visa VAMP is the Visa Acquirer Monitoring Program, which tracks fraud reports and disputes on card-not-present transactions for merchants and acquirers. It replaced Visa's separate dispute and fraud monitoring programs on April 1, 2025.

How is the VAMP ratio calculated?

The VAMP ratio equals the count of TC40 fraud reports plus TC15 disputes, divided by the count of settled card-not-present transactions in the same month. Transaction values do not matter, only the counts.

What is the VAMP threshold for merchants in 2026?

Since April 1, 2026, merchants in the US, Canada, Europe, and Asia Pacific are Excessive at a ratio of 1.5% or more with at least 1,500 counted fraud reports and disputes. The CEMEA region uses a 2.2% merchant threshold.

Do RDR disputes count toward VAMP?

Non-fraud disputes resolved through RDR or CDRN are excluded from the VAMP ratio. Fraud-related cases resolved through those tools still count, following a rule change Visa made in March 2025.

What is the VAMP enumeration ratio?

The enumeration ratio measures card testing by comparing enumerated authorization attempts with all authorization attempts. A merchant is identified at 20% or higher with at least 300,000 enumerated transactions in a month.

What happens if a merchant exceeds the VAMP threshold?

In the US, an Excessive merchant can be charged $8 per counted fraud report and dispute, usually passed on by the acquirer. Acquirers may also add reserves, raise rates, require a remediation plan, or close the account.
Picture of Charity Amancio

Charity Amancio

Charity Amancio specializes in SaaS solutions for global eCommerce businesses, including payments and risk management applications. She bridges the gap between technology and merchant needs, offering practical perspectives on the tools shaping eCommerce. Her insights appear regularly in B2B publications covering the digital commerce space.

Tags: Visa Dispute Monitoring Program
TweetShareSend
Previous Post

NICE’s Inaugural International Happiness Index Finds 78% of People Think Leveraging AI In Customer Service Can Make Them Happier Consumers

Next Post

Provenir Launches Onboarding Fraud Solution to Fight Back Against Fraudsters, Minimizing Losses While Safeguarding Customer Experience

Next Post
Provenir Launches Onboarding Fraud Solution to Fight Back Against Fraudsters, Minimizing Losses While Safeguarding Customer Experience

Provenir Launches Onboarding Fraud Solution to Fight Back Against Fraudsters, Minimizing Losses While Safeguarding Customer Experience

Search:

No Result
View All Result

Our Latest Reports

Fraud Trends Report

Consumer Payments Survey Report

Fraud Prevention Tactics that Enable Exceptional Customer Experience

ATO Fraud In Retail Report

3 Ways a Unified Chargeback Management and Fraud Platform Increases Revenue

Digital Trust And Safety Report: Combating the Evolving Complexities of Payment Fraud

On-Demand Webinars

New Trends in The Payments Ecosystem

Balancing Customer Experience and Fraud Prevention: What’s the Secret?

Stopping Fraud Across the Customer Lifecycle

Addressing Payment Fraud and the Customer Experience in 2022


Quick Navigation

  • Home
  • News
  • Join Us
  • About Us
  • Contact Us
  • Advertise
  • Contribute
  • Privacy Policy

Privacy Policy

Our Privacy Policy
Our Terms of Use

Resources

  • Articles
  • eCommerce Fraud Reports
  • eCommerce Fraud Webinars
  • Associations and Non-Profits
  • Podcasts
  • Vendor Directory
  • Chargeflow – AI Chargeback Management

Featured Vendors

  • Signifyd
  • TransUnion
  • PayRetailers
  • Spotrisk
  • CB-ALERT
  • Chargeflow
  • Corepay
  • AtData
No Result
View All Result
  • About Merchant Fraud Journal
    • Interested in Contributing or Guest Posting to Merchant Fraud Journal?
    • Merchant Fraud Journal Editorial Guidelines
  • Advertise on Merchant Fraud Journal
  • Articles
    • Chargebacks
    • Fraud Prevention
    • Influencer Insights
  • Contact Us
  • Download Addressing Payment Fraud and Customer Experience Report
  • Download Chargebacks Consumer Survey Report 2022
  • Download Evolving Complexities of Payment Fraud Report
  • Download Fraud Prevention Tactics that Enable Exceptional Customer Experiences Report
  • Download Merchant Fraud Journal 2023 Fraud Trends Report
  • Download Merchant Fraud Journal 2024 Fraud Trends Report
  • Download Merchant Fraud Journal Generative AI Fraud Prevention Checklist for SMBs
  • Download Quantifying the Challenge of Friendly Fraud: Your Post-purchase Strategy for the Future
  • Download the 2020 Chargeback and Representment Report
  • Download the 2020 Merchant Fraud Journal Vendor Guide
  • Download the 2021 Fraud Trends Report
  • Download the 2022 Fraud Trends Report
  • Download the 2023 Consumer Payment Trends Report
  • Download the 3 Ways a Unified Chargeback Management and Fraud Platform Increases Revenue Report
  • Download the MFJ 2022 Customer Experience Report
  • Download the MFJ ATO in Retail Report
  • Home
  • Home Elementor
  • Job Dashboard
  • Join The Merchant Fraud Journal Community
  • Merchant Fraud Journal Advertising Agreement
  • Merchant Fraud Journal Advertising Agreement – Signifyd
  • MFJ Fraud Trends Report Giveaway
  • News
  • Post a Job
  • Privacy Policy
  • Resources
    • #9978 (no title)
    • 2020 Chargeback Representment Guide for Merchants
    • 2020 Vendor Guide
    • 2023 Consumer Payments Survey Report
    • 3 Ways a Unified Chargeback Management and Fraud Platform Increases Revenue
    • 8 Fraud Prevention Training and Certifications: A 2026 Guide
    • Addressing Payment Fraud and the Customer Experience in 2022
    • Associations and Non-Profits
    • ATO Fraud In Retail Report
    • Balancing Customer Experience and Fraud Prevention: What’s the Secret?
    • Chargebacks Consumer Survey Report 2022
    • Digital Trust & Safety: Combating the Evolving Complexities of Payment Fraud
    • eCommerce Fraud Reports
    • eCommerce Fraud Webinars
    • Fraud Prevention Tactics that Enable Exceptional Customer Experiences
    • How to Build a Recession Proof Chargeback Prevention Strategy
    • How to Reduce Customer Friction During Holiday Sales Season
    • How to Stop Fraud During the 2022 Holiday Season
    • Jobs Board
    • Merchant Fraud Journal 2023 Fraud Trends Report
    • Merchant Fraud Journal’s Fraud Trends 2020 Report
    • Merchant Fraud Journal’s Generative AI Fraud Prevention Report: A Checklist for SMB Companies
    • Merchant Fraud Journal’s Fraud Trends 2021 Report
    • Merchant Fraud Journal’s Fraud Trends 2022 Report
    • MFJ’s 2022 Customer Experience Report
    • Podcasts
    • Prevent High-Velocity Fraud Attacks During the 2021 Holiday Season
    • Quantifying the Challenge of Friendly Fraud: Your Post-purchase Strategy for the Future
    • Stopping Fraud Across the Customer Lifecycle
    • The surprisingly easy way to secure your payment data, reduce your risk, and win the war on ecommerce fraud
    • Vendor Directory
    • Webinar – Addressing Payment Fraud and the Customer Experience in 2022
    • Webinar – Mitigating Fraud and Risk on the ACH Network
    • Win January Chargeback Disputes
  • Subscribed
  • Terms and Conditions

© 2026 Merchant Fraud Journal

Not enough quota to unlock this post
Unlock left : 0
Are you sure want to cancel subscription?