

Friendly fraud is when a cardholder disputes a legitimate purchase with their bank instead of asking the merchant for a refund, so the merchant loses the sale, the merchandise, and a chargeback fee at the same time. The industry also calls it first-party misuse, because the person filing the dispute is the real cardholder (or someone in their household) rather than a criminal using stolen card details.
Some cases of friendly fraud are honest mistakes, like a forgotten subscription or an unfamiliar billing descriptor, while others are deliberate attempts to keep the goods and the money. Card networks now describe friendly fraud as a leading cause of chargebacks, and forecasts show its share of disputes climbing through 2031, which makes spotting and fighting it a core skill for every online merchant.
Friendly Fraud at a Glance
- Friendly fraud is a chargeback filed by the actual cardholder on a purchase they or their household really made.
- Visa estimates it makes up around 20% of fraudulent disputes globally, and up to 30% for high-volume online merchants.
- Juniper Research forecasts friendly fraud losses rising from $8.1 billion in 2026 to nearly $16 billion in 2031.
- Merchants win these disputes with evidence: delivery proof, login and device records, customer service history, and Visa Compelling Evidence 3.0 data.
What Is Friendly Fraud?
Friendly fraud is a dispute that looks like fraud on paper but involves a transaction the cardholder authorized. The customer tells their issuing bank the charge was unauthorized, the item never arrived, or the product was not as described, even though the purchase was valid. Because the claim comes from the real account holder, it passes the identity checks that stop criminals, which is why it is so hard to block at checkout.
Accidental vs. Intentional Friendly Fraud
Accidental friendly fraud happens when a customer genuinely does not recognize a charge. Common causes include a billing descriptor that doesn’t match the store name, a subscription renewal they forgot about, or a family member who used a saved card. Intentional friendly fraud happens when the customer knows the charge is valid and disputes it anyway to get a free product, sometimes called cyber-shoplifting. Both types cost the merchant the same amount, but accidental cases are far easier to prevent with clearer communication.
How Friendly Fraud Works
Friendly fraud starts with a real transaction. A cardholder uses their own card, completes checkout, and receives the promised product or service. Later, they file a dispute with their card issuer, claiming the charge was unauthorized, the item never arrived, or the purchase was not as described.
Card issuers must investigate these claims under consumer protection rules like the Fair Credit Billing Act, which gives cardholders in the United States the right to dispute inaccurate or unauthorized charges. That legal protection shields genuine victims of fraud, but it also gives dishonest or confused customers an easy path to a refund without ever contacting the merchant first.
When the issuer sides with the cardholder, the bank reverses the payment, and the merchant absorbs the loss. Unlike a standard return, the merchant typically keeps neither the payment nor a chance to recover the merchandise, and a chargeback fee gets added on top of the lost revenue.
Friendly Fraud vs. Other Types of eCommerce Fraud
Friendly fraud sits in a different category than most fraud merchants prepare for. A quick look at the different types of eCommerce fraud helps clarify where it fits: friendly fraud is classified as first-party fraud because the person disputing the charge is the actual cardholder, not a criminal using stolen information.
True credit card fraud, the kind covered in-depth in our guide to credit card fraud, involves someone using stolen card numbers or account credentials to make purchases the real cardholder never authorized. Friendly fraud produces similar-looking chargeback reason codes on the surface, but the intent and identity of the person filing the dispute are completely different, which is exactly why standard fraud-screening tools struggle to catch it before the sale goes through.
Friendly Fraud vs. Chargeback Fraud vs. Credit Card Fraud
These terms get used interchangeably, but they describe different problems. A quick look at the different types of eCommerce fraud shows where friendly fraud fits: it is first-party fraud, while true credit card fraud, covered in our guide to credit card fraud, is third-party fraud committed with stolen credentials.
Friendly fraud vs. chargeback fraud vs. credit card fraud
| Friendly Fraud | Chargeback Fraud | Credit Card Fraud | |
|---|---|---|---|
| Who files the dispute | The real cardholder or a household member | The real cardholder | The real cardholder, after a criminal uses their card |
| Was the purchase authorized? | Yes | Yes | No |
| Intent | Accidental or deliberate | Always deliberate | Criminal third party |
| Typical reason codes | Unauthorized, item not received, not as described | Same as friendly fraud | Unauthorized or card-absent fraud |
| Main defense | Clear descriptors, communication, compelling evidence | Compelling evidence, blocking repeat disputers | Fraud screening, AVS, 3D Secure |
Source: Merchant Fraud Journal
Many merchants treat chargeback fraud as the deliberate subset of friendly fraud. The distinction matters because accidental cases respond to better communication, while deliberate cases require evidence and, in repeat situations, refusing future orders.
Common Causes of Friendly Fraud
Friendly fraud doesn’t always come from bad intent. Some disputes come from confused or forgetful customers, while others come from shoppers who understand exactly how the chargeback system works and use it to their advantage.
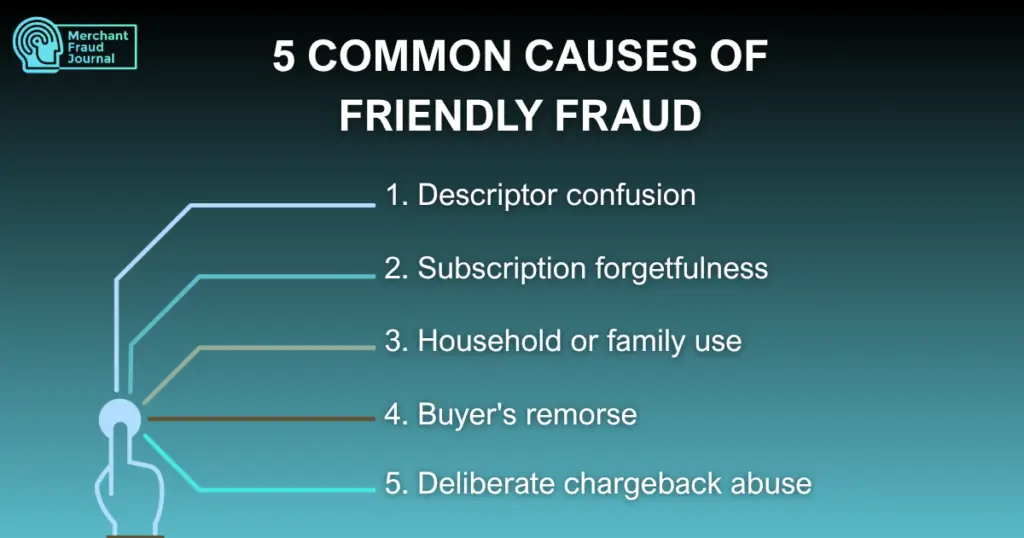
Recognizing the most common triggers makes it easier to spot patterns and adjust store policies before disputes pile up.
- Descriptor confusion: the customer doesn’t recognize the merchant name on their statement and disputes the charge as unauthorized.
- Subscription forgetfulness: the shopper forgets about a recurring plan and disputes the renewal instead of canceling directly with the merchant.
- Household or family use: a family member uses a shared card without telling the account holder, who later disputes the unfamiliar charge.
- Buyer’s remorse: the customer decides after the fact that they no longer want the item and disputes rather than requesting a standard return.
- Deliberate chargeback abuse: the shopper knowingly disputes a legitimate purchase to keep both the product and the money, sometimes described as cyber-shoplifting.
Some of these triggers point back to gaps in the merchant’s own processes. Unclear billing descriptors, slow customer service, and complicated refund policies may push honest shoppers toward the dispute button instead of the merchant’s support line.
Friendly Fraud Examples
Friendly fraud rarely looks the same twice, which is part of what makes it so hard for merchants to spot and fight. These scenarios show how friendly fraud typically plays up in eCommerce:
- The unrecognized charge: A customer buys running shoes from a store whose statement descriptor shows the parent company’s legal name. A month later they don’t recognize it and report it as fraud.
- The “never arrived” claim: A shopper receives a laptop with signed delivery confirmation, then tells their bank the package never showed up.
- The forgotten renewal: A subscriber skips the cancellation email, sees the annual charge, and disputes it rather than asking for a refund.
- The teenager’s in-game purchases: A child buys digital items on a parent’s saved card, and the parent disputes the charges as unauthorized.
- The post-return-window dispute: A customer misses a 30-day return window and files a “not as described” chargeback to get their money back anyway.
Many of these disputes can be prevented with simple fixes like clear statement descriptors, renewal reminders, and easy-to-find refund options. For the cases you can’t prevent, keep detailed records such as delivery confirmations, customer communications, and purchase logs so you have strong evidence ready when a chargeback arrives.
Why Friendly Fraud Is Growing
Friendly fraud is no longer a minor cost of doing business. Visa reports that friendly fraud accounts for around 20% of all fraudulent disputes globally, with that share climbing to as much as 30% for high-volume online merchants.
The Merchant Risk Council’s 2026 Global eCommerce Payments and Fraud Report, which surveyed more than 1,200 merchants across 35-plus countries, found that 64% of merchants reported a meaningful increase in first-party misuse over the past year, with roughly a quarter of them seeing increases of 25% or more.
That trend is even sharper at the enterprise level. The 2026 Chargeback Field Report found that more than 83% of enterprise merchants reported a rise in friendly fraud over the past three years, and nearly three-quarters of all merchants surveyed now describe it as a moderate or significant business concern.
Forecasts suggest the problem will keep compounding. Juniper Research projects that friendly fraud will climb from 22% of global chargebacks in 2026 to 28% by 2031, driven largely by consumers who increasingly view chargebacks against merchants as a victimless way to resolve a purchase they regret.
The Cost of Friendly Fraud to Merchants
A single friendly fraud chargeback costs more than the order itself. The merchant loses the revenue, the merchandise or service, the chargeback fee, and the staff time spent building a response. Credit card fraud statistics show how quickly these costs compound as dispute volume climbs.
Repeated disputes also threaten a merchant’s standing with the card networks. On April 1, 2026, the excessive merchant threshold in Visa’s Acquirer Monitoring Program (VAMP) dropped from 2.2% to 1.5% in most regions. VAMP counts both fraud reports and disputes, so friendly fraud claims push merchants toward that line just like real fraud does.
How to Identify Friendly Fraud
Catching friendly fraud early starts with disciplined monitoring, not guesswork. Effective merchant fraud monitoring involves tracking practices that flag suspicious dispute patterns, such as one customer filing multiple claims or a spike in “item not received” disputes tied to one shipping method or region.
Larger operations often assign this work to a dedicated fraud analyst. Separating a genuine complaint from a customer gaming the dispute process takes specialized skill and consistent documentation.
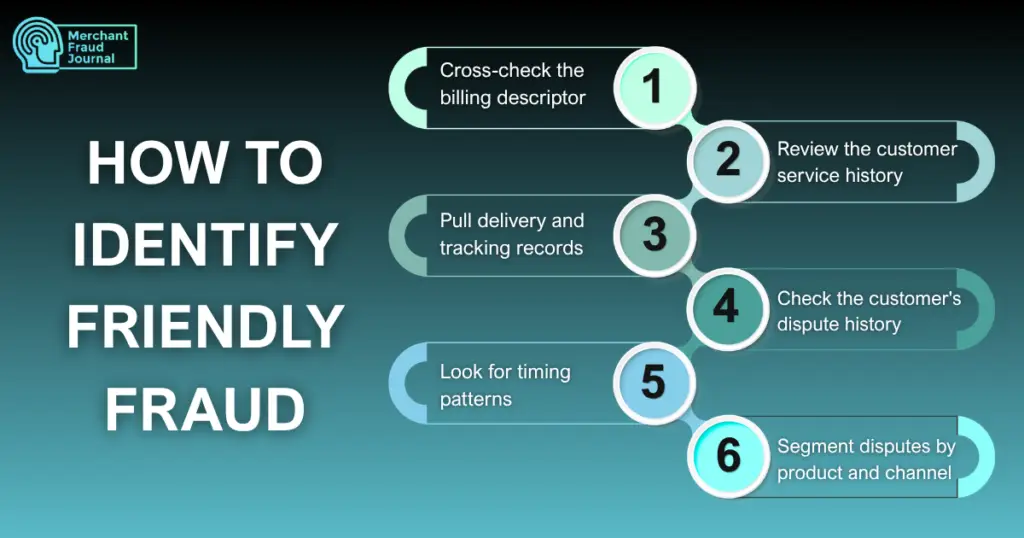
1. Cross-check the billing descriptor
Confirm whether the customer contacted support about an unrecognized charge before disputing it, since a mismatch they never questioned is a common friendly fraud signal. If the descriptor is unclear or doesn’t match the storefront name, update it immediately to prevent this trigger on future orders.
2. Review the customer service history
Look for any prior contact from the customer about the order; a dispute with no earlier complaint often points to a chargeback filed out of convenience rather than a genuine issue. A customer who skipped support entirely and went straight to their bank is worth flagging for closer review before contesting the case.
3. Pull delivery and tracking records
Compare proof of delivery, signature confirmation, or digital access logs against the customer’s claim that the item never arrived or was never used. This evidence often settles the dispute on its own, since a signed delivery receipt or an active login after the claimed non-use date directly contradicts the customer’s story.
4. Check the customer's dispute history
Flag repeat disputers who have filed similar chargebacks before, since a pattern across multiple orders is a stronger signal than any single case. Merchants who track this history across their customer base can proactively deny future orders from serial disputers before another loss occurs.
5. Look for timing patterns
Note whether the dispute was filed immediately after delivery, right before a return window closed, or shortly after a subscription renewal, since timing often reveals intent. A dispute that lands the same week a return window expires suggests the customer chose a chargeback specifically to bypass the merchant’s own policy.
6. Segment disputes by product and channel
Track which SKUs, shipping methods, or regions generate disproportionate dispute volume, since concentrated spikes usually point to a specific process gap rather than random chance. Isolating the pattern lets merchants fix the root cause, whether that’s a confusing product listing or an unreliable carrier, instead of treating every dispute as an isolated incident.
Consistent monitoring turns friendly fraud from a string of one-off surprises into a pattern that teams can actually manage. Each signal on its own rarely proves intent, but together they help separate a genuine complaint from a customer gaming the dispute process. Making this review a standard step for every chargeback gives merchants the documentation they need before they reach the representment stage.
How to Prevent and Fight Friendly Fraud
A layered approach cuts how often friendly fraud happens and improves the odds of winning the disputes that still come through. Here are steps to protect eCommerce merchants from friendly fraud and win chargeback cases.
- Use a recognizable billing descriptor that matches your storefront name, and include a support phone number or URL where the card network allows it.
- Send clear order, shipping, and renewal notifications so customers can connect a charge to a purchase before they call their bank.
- Make refunds and cancellations easy to find so contacting the merchant feels simpler than filing a chargeback.
- Use network pre-dispute tools such as Verifi Order Insight and Rapid Dispute Resolution (RDR) from Visa, and Ethoca alerts from Mastercard. These share order details with issuers or flag disputes early, so merchants can resolve them or refund them before a chargeback is recorded.
- Capture evidence at every step, including IP addresses, device IDs, delivery confirmations, login activity, and customer service communications.
- Layer checkout authentication such as AVS and 3D Secure, while recognizing these tools mainly stop third-party fraud rather than friendly fraud
These tactics work best together, and are often cited as best practices to prevent eCommerce fraud.
Using Visa’s Compelling Evidence 3.0
Visa’s Compelling Evidence 3.0 (CE3.0) framework lets merchants overturn invalid fraud-coded disputes with structured transaction data. According to Visa, merchants must show at least two prior undisputed transactions from the same cardholder, older than 120 days, that share matching data points such as IP address or device ID. Merchants who collect this data consistently at checkout have a far stronger case than those who try to reconstruct it after a dispute lands.
Start Cutting Friendly Fraud Losses Today
Friendly fraud is growing, but it is manageable. Merchants who fix descriptors and communication gaps prevent accidental cases. Collecting evidence at every transaction and treating every chargeback as a pattern to review lets them win more of the deliberate ones. That combination protects revenue, keeps dispute ratios below card network thresholds, and stops honest customers from paying for dishonest ones through higher prices.
Frequently Asked Questions
What is meant by friendly fraud?
Friendly fraud means a cardholder disputes a purchase they or someone in their household actually made, claiming it was unauthorized, undelivered, or not as described. It is also called first-party misuse, because the real account holder files the dispute rather than a criminal using stolen card details.
Is friendly fraud actually illegal?
Friendly fraud violates the cardholder agreement even when it isn't prosecuted as a crime. Merchants can report repeated intentional cases to card networks and, in serious situations, to law enforcement.
How do merchants dispute a friendly fraud chargeback?
Merchants dispute a friendly fraud chargeback through representment, submitting evidence such as delivery confirmation, login and device records, order details, and customer communications to the issuing bank. For Visa fraud disputes, Compelling Evidence 3.0 data showing prior undisputed purchases with matching IP addresses or device IDs can overturn the claim.
Can merchants win a friendly fraud dispute?
Merchants can win through the representment process by submitting evidence like delivery confirmation, order records, and customer communication history. Win rates vary by industry and evidence quality, but strong documentation meaningfully improves the odds.
How is friendly fraud different from a normal return?
A return happens directly between the customer and the merchant, while friendly fraud routes the dispute through the card issuer instead. That path skips the merchant's own refund process entirely and adds network fees on top of the lost sale.
Does friendly fraud affect all industries equally?
No, digital goods, subscriptions, and high-ticket items tend to see disproportionately higher friendly fraud rates. Physical goods with clear delivery tracking generally see fewer successful disputes.
Can you go to jail for friendly fraud?
Jail time for friendly fraud is rare, because most cases are handled as disputes between the cardholder, the bank, and the merchant. Knowingly filing false chargebacks can still be prosecuted as theft or fraud in some jurisdictions, especially when the amounts are large or the behavior is repeated.
How to stop friendly fraud before it happens?
Setting expectations at checkout, such as delivery windows and cancellation terms, prevents the misunderstandings that often lead to a dispute. Fraud-scoring tools that flag repeat disputers help merchants intervene before the pattern repeats.